BREAKING NEWS…
by Bloomberg | 12 Sep 2016
Stricter Mortgage Rules for Banks
Canada’s financial regulator released proposed new mortgage rules that could see the country’s lenders hold more capital to offset risks.The draft guidelines have been updated to “reflect the changing risks in the Canadian mortgage market,” the Office of the Superintendent of Financial Institutions said in a statement. The watchdog said in December it would seek to shift the burden of risks to banks and away from taxpayers, part of a broader effort by government to address what some observers say is an overheated housing market.OSFI floated the policy as part of revised Capital Adequacy Requirements, or CAR, a set of rules governing federally-regulated banks, loan companies, and trusts and based on global requirements. The new CAR framework, published today, is open for comment until Oct.18. It will come into force as soon as November.
If a Canadian lender doesn’t follow the compliance policies set out by OSFI and the mortgage insurers, OSFI may “reduce the level of consideration of the mortgage insurance the lender is using as a guarantee to mitigate its credit risk," according to an agency spokeswoman. In addition, institutions are expected to have appropriate policies and procedures in place to originate, underwrite and administer insured mortgages," the agency said in a document posted to its website. Policy makers have warned that Canada’s housing market is overvalued in some cities and the government is keen to limit taxpayer exposure to any potential downturn. Federal Finance Minister Bill Morneau and the government-owned mortgage insurer, Canada Mortgage & Housing Corp., have floated the idea of banks being required to hold more capital for residential mortgages to protect against defaults.
Morneau said this week additional measures may be needed to manage the risks associated with the “highly charged” Vancouver and Toronto housing markets, even after British Columbia imposed a 15 percent tax on foreign buyers to curb price gains.Under current guidelines, lenders are required to maintain a certain amount of capital to back mortgages, as well as to comply with OSFI risk-mitigation rules. Under the proposed rules, if OSFI determines a lender isn’t following policy, it may reconsider whether its mortgage insurance adequately covers the loan risk, prompting the lender to take further steps, including shoring up capital.
Copyright Bloomberg 2016
#mortgagenews #mortgages #realestatemortgages
Durham Region is a great place for 1st -time buyers to get into the market and build equity. The expansion of the 407 and government investment in Go Train expasion and the shortgage of listings - home prices continue to rise. My advise for 1st time buyers is to find an acitve full time Realtor that is experienced studies the market and pricing daily, has a good knowledge of home construction and good negotiating skills to represent you to resolve problems that come up during home inspections. Buying a home in today's market is hard work, you need to commit the time required to get out and view homes when they come up on the market and don't get discouraged you will be rewarded for your efforts. I understand that buying your 1st home should be fun and wonderful experience, yet with today's market conditions, if your commited and don't give up the fun will come when you quit paying rent and move into your home!
Here is a link to a search I created for 1st Time Buyers Check out the listings.
It will provide you valuable information not available on Realtor.ca, for all MLS listings.
You can create your own search and make it specific to your
In today's market homes are selling for over list price. We study the market everyday and have 20 years experience ensuring our clients get the best results.
For all your Real Estate and Mortgage needs, Call Jim Stanton and Associates Today! We are ready to go to work for you!
#1stTimeBuyers #DurhamRealEstate
Sales still strong with prices on the rise for #MyFallingbrook Neighbourhood for the month of August 2016

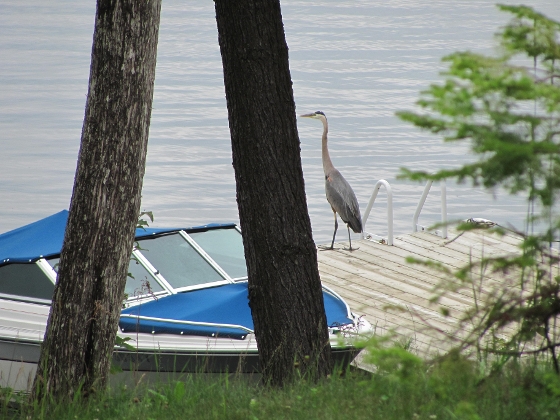
You’ve been vacationing renting a cottage in Halliburton or the Kawartha's with a beautiful lakefront shoreline.
It's not uncommon for many vacationers to find themselves checking out the local real estate listings in between boating or sightseeing. However, many vacationers aren't just looking, they're buying!
Royal LePage recently released a comprehensive report on the recreational real estate industry in Canada, entitled the 2016 Canadian Recreational Housing Report, which found a growing number of investors are turning to this lucrative segment.
According to the report, 49% of recreational property buyers purchased for the purpose of investing; 64% of advisors polled said potential purchasers purchase for the sake of retirement.
So is a vacation or 2nd home the right buy for you?
It depends on how you plan to use the home (recreation versus retirement nest, for example) and your balance sheet. You may want to rent out your 2nd home or cottage to recover expenses such as property taxes or mortgage costs.
You may consider buying a property off the water with deeded water access. These properties are more affordable - lower property taxes with deeded access complete with dock to the lake your home or cottages overlooks. Areas where my clients have purchased homes with deeded water access have been in Bobcaygeon and Ennismore.
Remember when your cottage has a location in a desirable area, you can almost always count on being able to resell if you need to.
Other tips for buying a vacation home:
Research an area thoroughly.
The better you know an area, the more predictable the consequences of buying there. Make sure you talk to other property owners, not just the local real estate agency.
If you purchase in a more remote area, for example, find out if there are security concerns with homes that are empty part of the year.
Check out resale statistics, too, as well as property taxes. Poor resale rates could prove burdensome if you need or want to sell in the future.
Onerous property taxes may tip your balance sheet against the purchase.
Get good tax advice.
If you rent out your vacation property part of the year, that rental income is added to your own income. However, you can deduct some of the expenses connected with renting out your own property, such as paying for a cleaning service or a rental agent.
Cover all the tax bases because in some cases, it may make more sense to continue renting rather than buying.
Other tips we suggest you check out:
Also a phone call from a knowledgeable Realtor can save you hours of time.



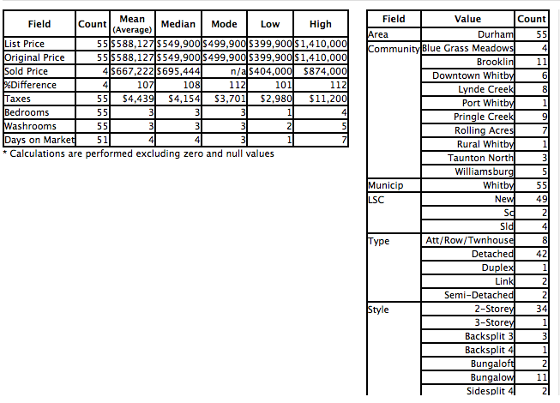
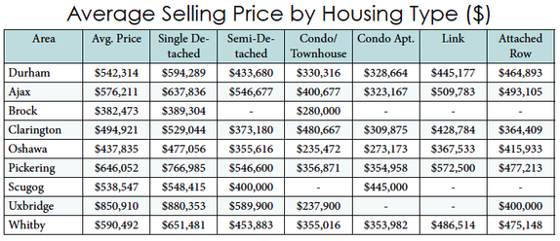
Week 1 August 2016 Sales Stats for #MyFallingbrook Neighbourhood

#MyFallingbrook #PringleCreek #WhitbyRealEstate
information take from the Toronto Real Estate Board
Durham Region Association of REALTORS® (DRAR) President Sandra O’Donohue reported 1,471 residential transactions in June 2016. A slight increase compared to the same period last year. “Demand continues to exceed supply,” stated O’Donohue. In contrast, there were 1,755 new listings in June 2016 compared to 1,796 June 2015; a 2.3 per cent decrease.
The president also confirmed my message to all my clients as to the added value to our real estate from the government investment in infastructure to Go Transit and 407 extention to our area.
The GO Transit’s Lakeshore East extension into Clarington demonstrates much needed attention to the transportation infrastructure in Durham Region. “With ease of use directly impacting commuters, the extension will greatly improve the value of homes and increase demand of properties in our neighbourhoods,” added O’Donohue. “It is inevitable that this will impact real estate and drive growth in Durham Region.”
Whitby Real Estate - Pringle Creek - Fallingbrook Neighbourhood 2016 Q1 and Q2 combined Sales Stats
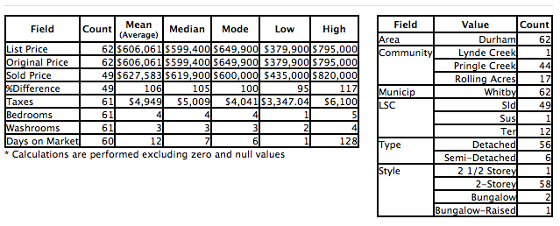
information taken from Toronto Real Estate Board MLS
#MyFallingbrookStats #MyFallingbrook Neighbourhood
#WhitbyRealEstate - Pringle Creek - Fallingbrook Neighbourhood